

CompatibL Platform for Trading and Risk Management
CompatibL Platform is a comprehensive trading and risk management software, offering rich trade lifecycle management, market and credit risk management solutions, liquidity and balance sheet forecasting, as well as limit and regulatory compliance functions for the entire investment portfolio.
The platform features advanced analytics and models across all product types, from vanilla instruments to complex derivatives with bespoke payoffs such as TARFs or autocallables, and delivers rich functionality for pre-trade analysis, real-time P&L, market and credit risk, back office, and regulatory compliance for multi-asset portfolios.
Trade Life Cycle
CompatibL Platform provides comprehensive end-to-end book-of-record functionality with full segregation of duties and four-eye sign-off across FO, BO, Ops, and other teams, trade events support, configurable settlement workflows and cash management.
Risk Analytics
The platform features advanced risk management tools with comprehensive reporting capabilities that allow financial organizations to easily run market, credit, and liquidity risk calculations on positions and portfolios.
Open Risk Architecture & Integration
CompatibL Platform is built around a high-performance analytics engine to provide high horizontal and vertical scalability, enabling real-time portfolio risk and P&L calculations with drilldown and aggregation all the way to the level of individual trades and market risk factors.
Comprehensive, Cloud-Driven Trading and Risk Solutions
Our credit risk software helps institutions effectively measure, monitor, and manage credit exposures across counterparties and portfolios. It includes advanced credit risk analytics and reporting capabilities suitable for enterprise-scale implementations.
It also offers comprehensive limit management and monitoring features, including PFE-based counterparty credit risk limits, real-time exposure updates, automated pre- and post-deal checks, margin simulations, and configurable alerts with escalation workflows to ensure timely response to limit breaches.
Market risk management software by CompatibL enables financial institutions to identify, measure, and mitigate exposure to market fluctuations across various asset classes.
It supports Value-at-Risk (VaR), scenario analysis, stress testing, and sensitivity calculations, helping organizations gain a holistic view of risk across portfolios.
Our regulatory capital software provides integrated data aggregation, analytics, and reporting to manage regulatory risk across asset classes and streamline complex workflows to ensure regulatory compliance.
It is aligned with key global frameworks and methodologies, including Basel III and IV, ISDA SIMM, IRRBB, FRTB, SA-CVA, BA-CVA, SA-CCR, Jump-to-Default (JTD), and Large Exposures (LEX), ensuring that financial organizations meet regulatory requirements with confidence
Cloud or On-Premises Deployment
CompatibL Platform can be deployed in your data center, private cloud, and in most public clouds, including AWS and Azure. It leverages the latest serverless cloud technologies, including AWS Fargate, Lambda, Step Functions, and Azure Functions. The platform supports both Windows and Linux traditional data centers and can run on top of all leading cluster management software solutions.

 Real-Time Risk Analytics
Use cloud or on-premises grid computing with the ability to run user-defined calculations on the cluster.
 Comprehensive Reporting
Full storage and customization of reporting capabilities based on HTML5 front-end technology.
 Advanced Analytics Libraries
Use a large number of CompatibL’s valuation and risk models or easily integrate your ecosystem with user-friendly APIs in Python, Java, C++, or C#.
 BI Tools and Interactive Dashboards
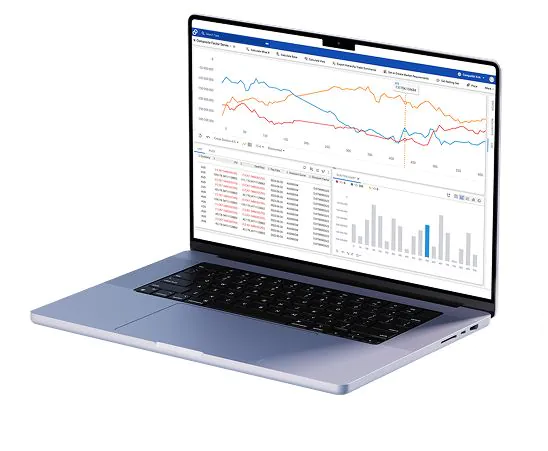
Our platform includes interactive dashboards that transform complex information into clear, actionable insights for better decision-making, helping visualize your risks for effective risk management and mitigation.
- Components
- Market Risk
- Credit Limits
- Tools
- Front-End
- Back-End
- Balance Sheet Management
- Advanced Features
Components
- Trade lifecycle, trade events, cash/DVP settlements
- Market risk scenarios, Greeks and cross gammas, historical/Monte Carlo/parametric VaR
- Liquidity risk: LCR, NSFR, LVAR
- Net interest income, constant balance sheet, dynamic balance sheet
- PFE and quantile measures, pre-/post-collateral, MPR
- XVA: CVA, DVA, FVA, KVA, COLLVA, MVA
- Credit limits: pre-settlement, settlement limits, debtor risk, issuer risk
- Pre- and post-trade analysis / what-if
- Basel III, IV, ISDA SIMM, IRRBB, FRTB, SA-CVA, BA-CVA, SA-CCR, JTD, LEX
- P&L explain, deltas/predict P&L
Market Risk
- Instantaneous shocks
- Parallel/non-parallel shocks
- Twists
- Relative and absolute magnitudes
- Bucketed/term structure scenarios
- Z-spread
- First-order/second-order Greeks
- Cross gammas
- Theta
- Survival probability/hazard rate
- Credit rating migration
- Composite scenarios
- Correlation
- Historical VaR, Monte Carlo VaR, parametric VaR
- P&L explain – full revaluation
- P&L attribution – Taylor expansion
- Backtesting
Credit Limits
- Risk types: replacement (pre-settlement CCR limits), settlement, issuer, debtor
- PFE-based CCR limits
- Variation margin (VM) and initial margin (IM) simulation
- Formula-based bucketed limit definition
- Hard and soft limits
- Flexible portfolio hierarchy
- Fast pre-deal checks (PDCs) based on reaggregation of the cached exposure
- Automated post-deal checks
- Real-time trade updates
- Limit explain dashboard
- Escalation process
- Limit breach notifications
Tools
The risk management software provides multiple tools that enhance productivity and processes.
- Excel add-in
- Server-side Excel spreadsheet processor
- Export in multiple formats (Excel, PDF, XML, CSV and others)
- Source code and script editor with syntax suggestions (IntelliSense)
- Log analyzer
- Application deployment and monitoring services
- Automated testing tools
- Code generation tools
Front-End
- Flexible and customizable React-based user interface
- High-performance HTML5 pivot view with virtualized rows and columns
- Business intelligence (BI) module
- Data grid/tables with the ability to aggregate and apply vector functions on the fly
- SQL and NoSQL databases and data stores (Mongo, Redis, MS SQL Server, Oracle, etc.)
- Rich UI component library
- Excel add-in working with the front-end or standalone
Back-End
- Cloud-based solution for AWS, Azure and other cloud platforms
- Batch services for Kubernetes
- Distributed cache for parallel calculations based on Redis or MongoDB
- Electronic trading support
- Event monitor
- Formula engine and structured derivatives payoff script
- Messaging adapters for standard protocols including RabbitMQ, JMS, TIBCO
- Bloomberg and Reuters market data adapters
- Workflow manager
Balance Sheet Management
Net interest income
- PV, BPV, fair value, book value, P&L
- Interest income profiles
- Simulation of future earnings, interest income, and market values
Constant balance sheet
- Prolongation assumption per product category
- Assumptions for new business
- Recalibration of spread/rate
Dynamic balance sheet
- Rollout assumptions
- Hedging constraints
Liquidity key figures
- LCR
- NSFR
- Time to wall
- LGF
Liquidity gap profile
- Balance sheet size
- Liquidity cash flow models
- Facility withdrawals
- Loan defaults
- Probabilistic defaults
- Instrument prolongation
- Asset sales
- Own issuance
- Machine learning models for non-maturing products
Advanced Features
- Import trade, market and reference data from multiple trading and risk systems
- Fast American Monte Carlo for complex derivatives
- Consistent model calibration for both market scenarios and trade prices
- Advanced modeling of dynamic hedging and collateral rules
- Flexible framework for using an external model for market simulation
- Stress testing and drill-down based on business unit, instrument type, desk, position, maturity bucket or custom factors
- Batch processing and workflow orchestrator and combining automated (calculations, feeds, etc.) and manual (e.g.approvals) steps
- Standard out of the box desk, regulatory, and fair value reports and reports customization
Use Cases for Risk Management Software
Why CompatibL
 Source Code Delivery
CompatibL is the only major vendor to provide source code for its entire platform, including analytics, to its clients. With full source code access, our clients can use AI coding tools to add new modules and enhancements to our platform or address emerging cybersecurity threats.
 Award-winning Vendor in Risk Management
Our innovative solutions were recognized by most prestigious awards in the industry, including the Risk Markets Technology Awards, WatersTechnology Buy-Side and Sell-Side Technology Awards, and American Financial Technology Awards.
 Focus on Software Development for Banks and Asset Managers
23+ years of experience in delivering complex business requirements for desk and enterprise risk.
 Cloud or On-Premises Risk Management Project
Track record of delivery of enterprise risk projects running on premises or in the cloud.
algorithms and technical architecture of the award-winning software solution
algorithms and technical architecture of the award-winning software solution
Our Customers Say